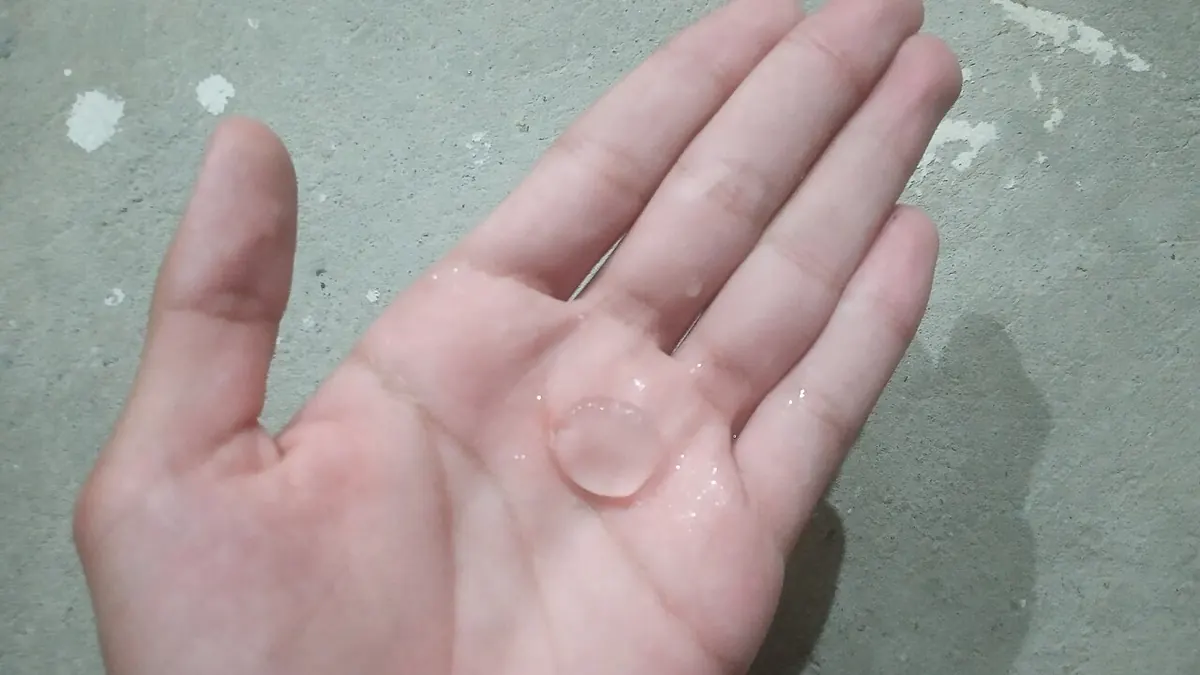
Hail in the Commonwealth
Kentucky sits in a path where spring storm systems routinely cross the Ohio Valley, and hail can hit anywhere from the Purchase to the Big Sandy. Suburbs around Louisville and Lexington, fast-growing areas near Bowling Green and Elizabethtown, and small towns in between all see seasons where entire neighborhoods file roof claims at once. When volume spikes, estimates get written quickly, and quick estimates are where scope gets missed.
Where roof estimates come up short
- Test squares and spot repairs: a carrier may count hits in a small sample area and approve a few shingles when damage is spread across every slope.
- Measurements: missed slopes, dormers, steep-pitch charges and waste factors change the total quickly.
- Matching: discontinued shingles or faded colors can make a patch look nothing like the rest of the roof.
- Accessories: drip edge, ice and water shield, starter, ridge cap, pipe boots and vents are easy to leave off.
- Soft metals and collateral: dented gutters, downspouts, window wraps and HVAC fins are part of the same storm.
- Metal roofs: the cosmetic-versus-functional question often depends on specific policy endorsements.
Our roof inspection approach
We walk the roof where it is safe, mark and photograph damage on every slope, and measure the roof ourselves rather than relying only on the carrier’s diagram. We note the shingle type and age, check whether the product is still made, and record collateral damage that supports the storm date. Our roof measurement calculator lets you sanity-check squares and pitch on your own before we arrive.
We also look beneath the surface where it matters. Bruised mat, fractured shingle reinforcement and granule loss in a hail pattern tell a different story than blistering or foot traffic. Where a roof has multiple layers, older decking or ventilation issues, we note those too, because they affect what a proper replacement actually involves and what the building code may require at tear-off.
Pricing the roof for your market
A roof in Pikeville and a roof in Covington may not cost the same to replace. We price labor and materials for the local market and include items such as tear-off, disposal, permits where required and steep or high charges when they apply. If general contractor overhead and profit is warranted because of multiple trades, we explain why in the estimate.
When appraisal is the right tool for a roof
Appraisal fits best when the insurer agrees hail or wind damaged the roof but disagrees on how much of it needs work or what it costs. If the carrier denies the claim outright, calls the damage wear and tear, or questions the date of loss, those may be coverage or causation disputes that appraisal handles differently depending on policy wording and Kentucky law. We’ll be straight with you about that. Wind-driven roof losses are also covered on our tornado and wind appraisal page, and you can reach us here to get started.
Questions about roof & hail damage appraisal
My adjuster approved a few shingles but my roofer says replace it. Can appraisal help?
Often, yes. Repair-versus-replace is a classic amount-of-loss dispute when the insurer already agrees the storm caused damage.
Can appraisal force the insurer to replace undamaged slopes so the roof matches?
Matching depends on policy language and how the carrier and appraisal panel treat it. We document the mismatch so the issue is squarely in front of the appraisers.
How long after a hailstorm can I still file?
Policies set their own reporting and suit deadlines, so check your policy promptly. Waiting can also make it harder to prove which storm caused the damage.