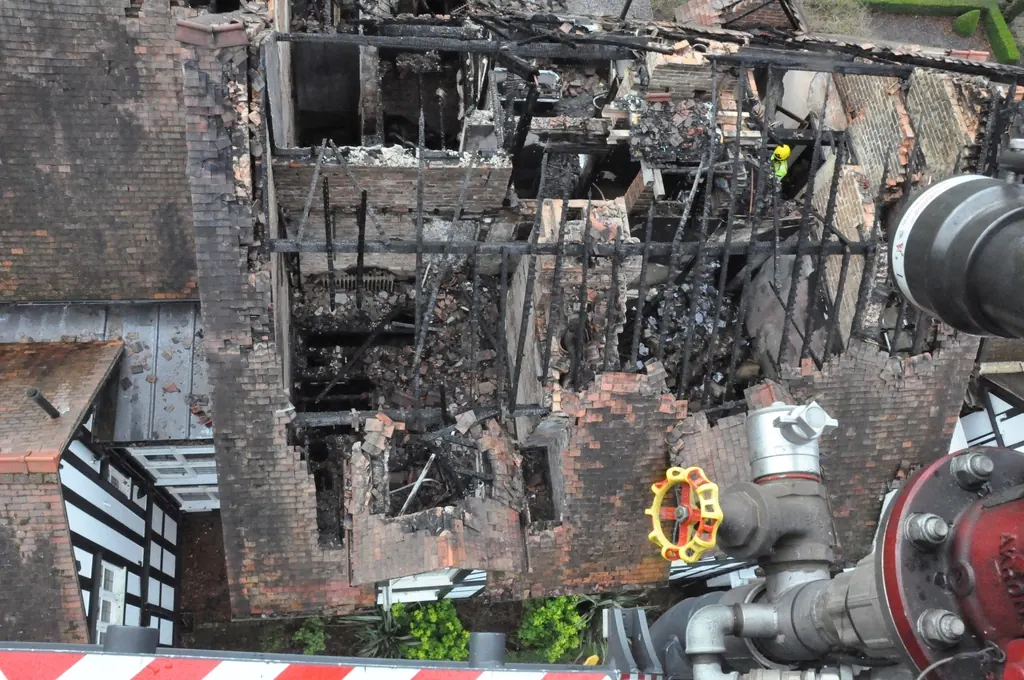
The scope beyond the burn
A fire that starts in a kitchen in Elizabethtown or a garage in Richmond rarely stays put. Heat damages framing and wiring well past the visible char. Smoke pushes into attic insulation, HVAC ducts, closets and wall cavities. Water from firefighting soaks floors and ceilings. A first estimate that focuses on the room of origin can leave large parts of the loss unpriced.
Lightning and fire in Kentucky
Kentucky’s thunderstorm season brings frequent lightning, and a strike can start an attic fire, travel through wiring and damage electronics, HVAC equipment and well pumps throughout the house. Rural homes and barns are especially exposed. When lightning is the cause, the claim often combines fire damage with power-surge losses, so we look at the electrical system and appliances along with the structure.
Smoke and soot disputes
The most common fight on a fire claim is clean versus replace. Insurers frequently propose cleaning and sealing surfaces that the owner believes are beyond saving. The answer depends on the type of residue, the material and how far odor has penetrated.
- Porous materials such as insulation, carpet pad and some ceiling textures often can’t be cleaned effectively.
- HVAC systems may need professional cleaning or component replacement to stop recirculating odor.
- Painted surfaces may need sealing and repainting in every affected room, not just the room of origin.
- Electronics and appliances exposed to corrosive soot can fail later even if they work today.
Fire-damaged homes also raise code questions. Rewiring, framing repairs and replaced mechanical systems may need to meet current standards, and whether the policy pays for those upgrades depends on ordinance-or-law coverage. We identify code-driven items separately so the coverage question and the pricing question don’t get tangled together.
Contents claims
For many families, the contents inventory is the hardest part. Listing everything in a home room by room, with age and replacement cost, is tedious and painful after a fire. Appraisal can address the value of covered contents when the insurer disputes pricing or depreciation. Many policies pay actual cash value first and the rest after replacement, so depreciation schedules matter. Our RCV and ACV holdback calculator shows how that withheld amount works.
Our role on a fire appraisal
We inspect the full structure, document heat, smoke and water damage separately, and write an estimate that reflects the restoration actually needed. Where specialized testing or an electrician’s report would settle a question, we recommend it. We then serve as your appraiser and work the gap with the insurer’s appraiser and, if needed, the umpire.
Fire claims sometimes involve questions about cause or policy conditions. Those are not appraisal questions, and we’ll suggest talking with a Kentucky attorney if they come up. For the broader process, see the Kentucky appraisal process overview, or get in touch to discuss your loss.
Questions about fire & smoke damage appraisal
Can appraisal decide whether smoke-damaged items should be cleaned or replaced?
Yes, in many cases. When the fire is accepted as covered, the cost of the proper restoration method is part of the amount of loss.
Are lightning surge losses part of a fire appraisal?
They can be if the policy covers them and the dispute is over the amount. Some policies treat surge damage differently, so check the wording.
Do I need a complete contents inventory before appraisal?
A detailed inventory makes the contents portion far stronger. We can help organize it, but you know what was in the home better than anyone.